Trucking Insurance in Douglasville, Explained Piece by Piece
We write primary auto liability, physical damage, motor truck cargo, bobtail and trailer interchange coverage for owner-operators, new-authority carriers, small fleets, and hotshot, box truck and dump truck businesses. You hear what each piece covers, what it costs you to leave it out, and why. We work with carriers in Douglasville, Lithia Springs and Villa Rica.
- In business 5 years
- Quotes by phone or video
- Every coverage explained plainly
- Help with certificates and filings
How a Quote Comes Together
Most of our work happens by phone or video, with the office open for anyone who prefers to sit down in person.
- 1
A conversation about your operation
We start with your DOT number, MC authority status, trucks, trailers, drivers and what you haul. A few minutes of detail here saves time later.
- 2
Gathering what insurers need
We collect driver information, vehicle details and any prior loss runs. For a new authority, we walk you through what is needed before your authority can go active.
- 3
Choices, explained
We present coverage choices with their trade-offs: limits, deductibles, stated values and any exclusions worth knowing about. You choose what fits your contracts and your budget.
- 4
Policy, filings and certificates
Once you decide, we place the coverage, take care of the required filings with regulators, and issue certificates of insurance to the brokers or shippers you name.
- 5
Staying current
When you add a truck, hire a driver or sign a new contract, call us and we update the policy. Before each renewal, we review the whole program with you.
Coverage Built Around How You Run
A trucking policy is assembled from separate coverages, and each one answers a different question: who pays if you hit someone, who pays to fix your truck, who pays for the load. We have been in business 5 years, and in that time we have learned that most coverage problems come from a piece that was missing or sized wrong, not from the price. Below you will find primary auto liability, physical damage, motor truck cargo, non-trucking liability, trailer interchange, and programs built for owner-operators, new authorities, fleets, hotshot, box truck and dump truck operations.
Commercial Trucking Insurance
The full set of coverage a motor carrier needs, from liability and filings to cargo and physical damage, assembled around how your trucks actually run.
Primary Auto Liability
The coverage your DOT number and MC authority depend on, with limits, filings and policy structure explained so you choose deliberately.
Physical Damage
Collision and comprehensive coverage for the truck and trailer themselves, with stated values and deductibles set to fit your loan and your cash reserves.
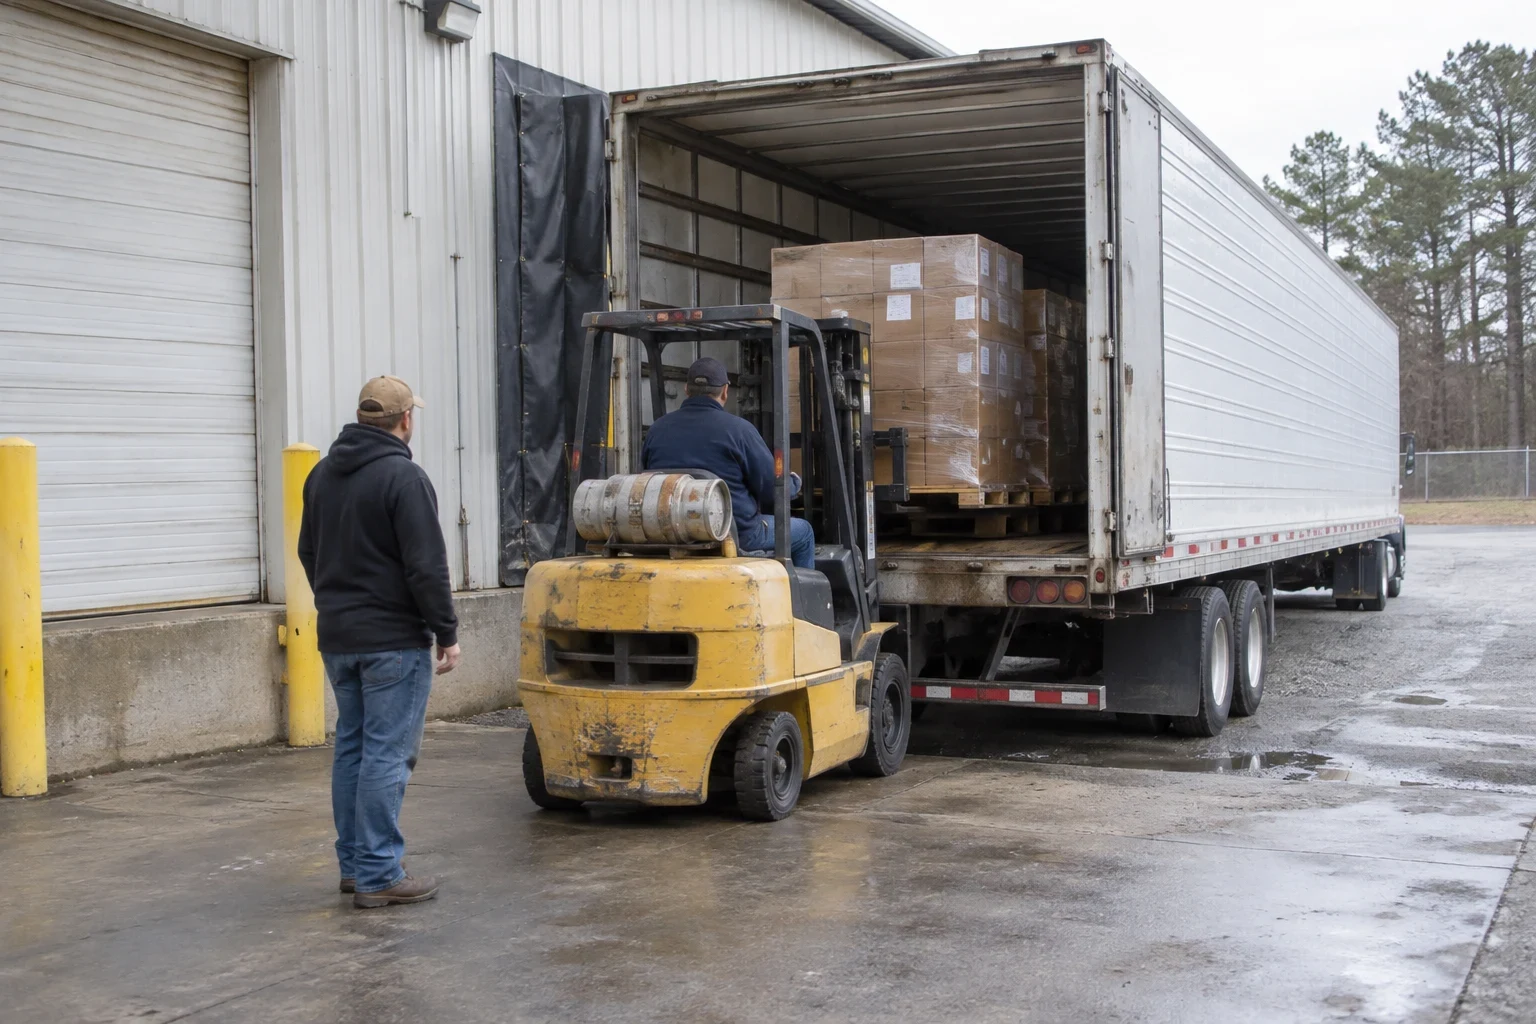
Motor Truck Cargo Insurance
Cargo coverage matched to what you haul, with the exclusions, limits and deductible explained in plain terms before you sign.
Non-Trucking Liability (Bobtail)
Liability coverage for leased owner-operators when the truck is off dispatch, with the policy wording compared so the gaps are clear before you sign.
Trailer Interchange
Physical damage coverage for trailers you haul under a written interchange agreement, sized to the trailers and contracts you actually work with.
Owner-Operator Insurance
Coverage built around how you actually run, leased to a carrier or under your own authority, with each piece explained before you sign.
New Authority Truck Insurance
Coverage and federal filings for motor carriers starting under their own MC authority, with each part of the policy explained before you commit.
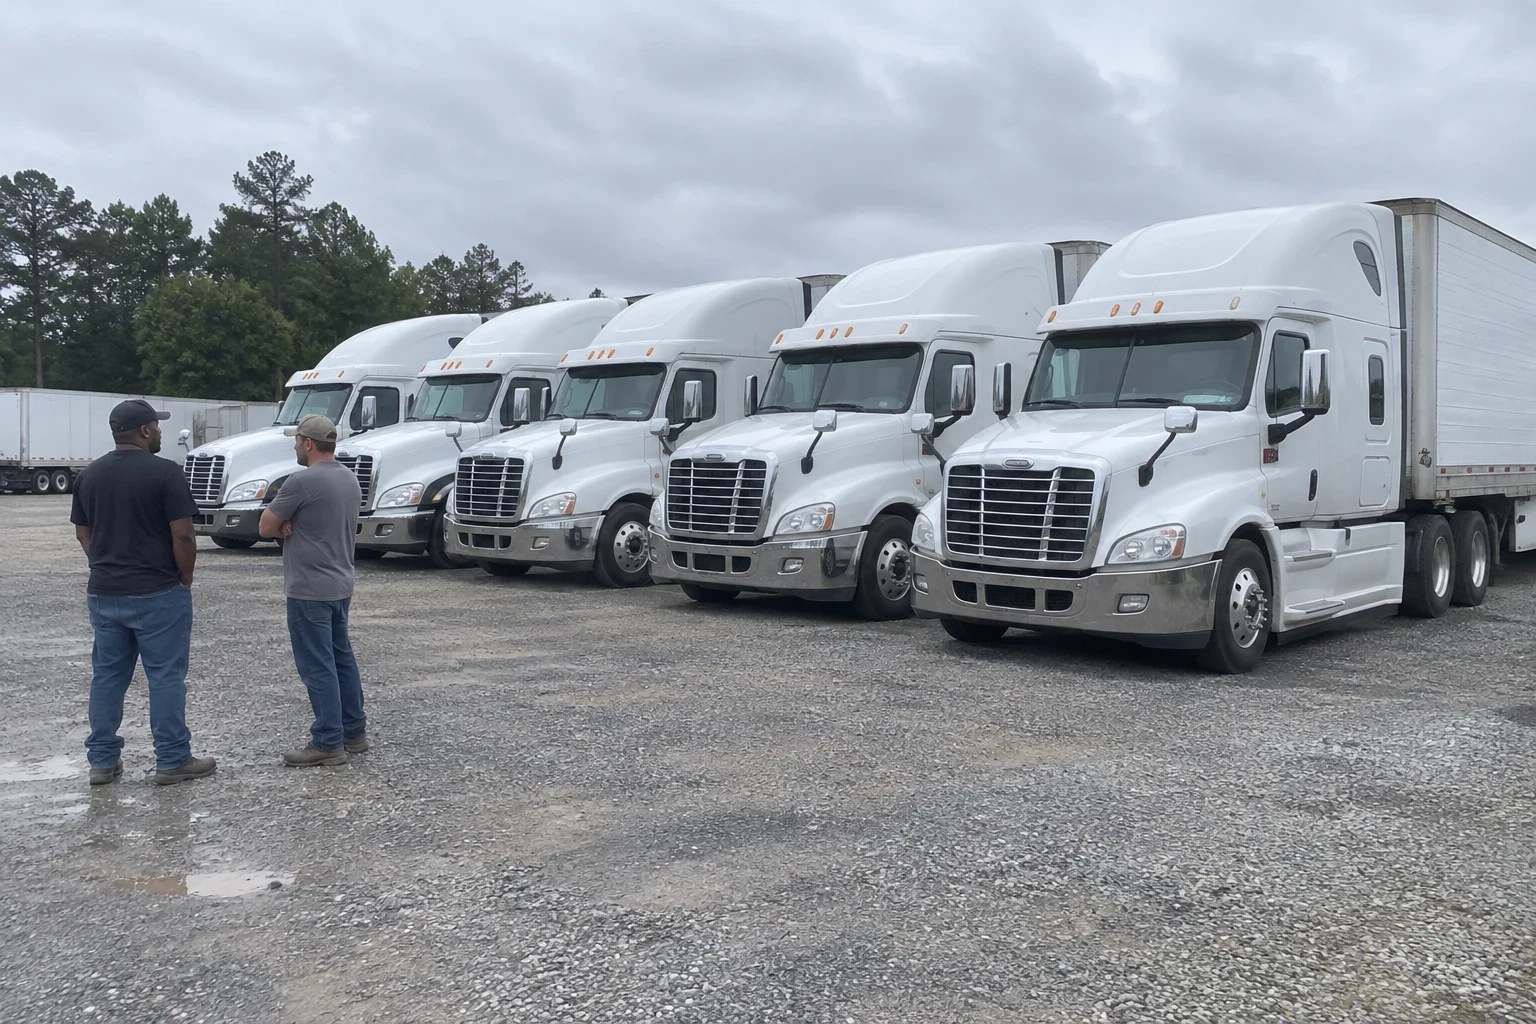
Fleet Truck Insurance
One policy for several trucks and drivers, with liability, physical damage, cargo and filings laid out so you can see what each piece costs and covers.
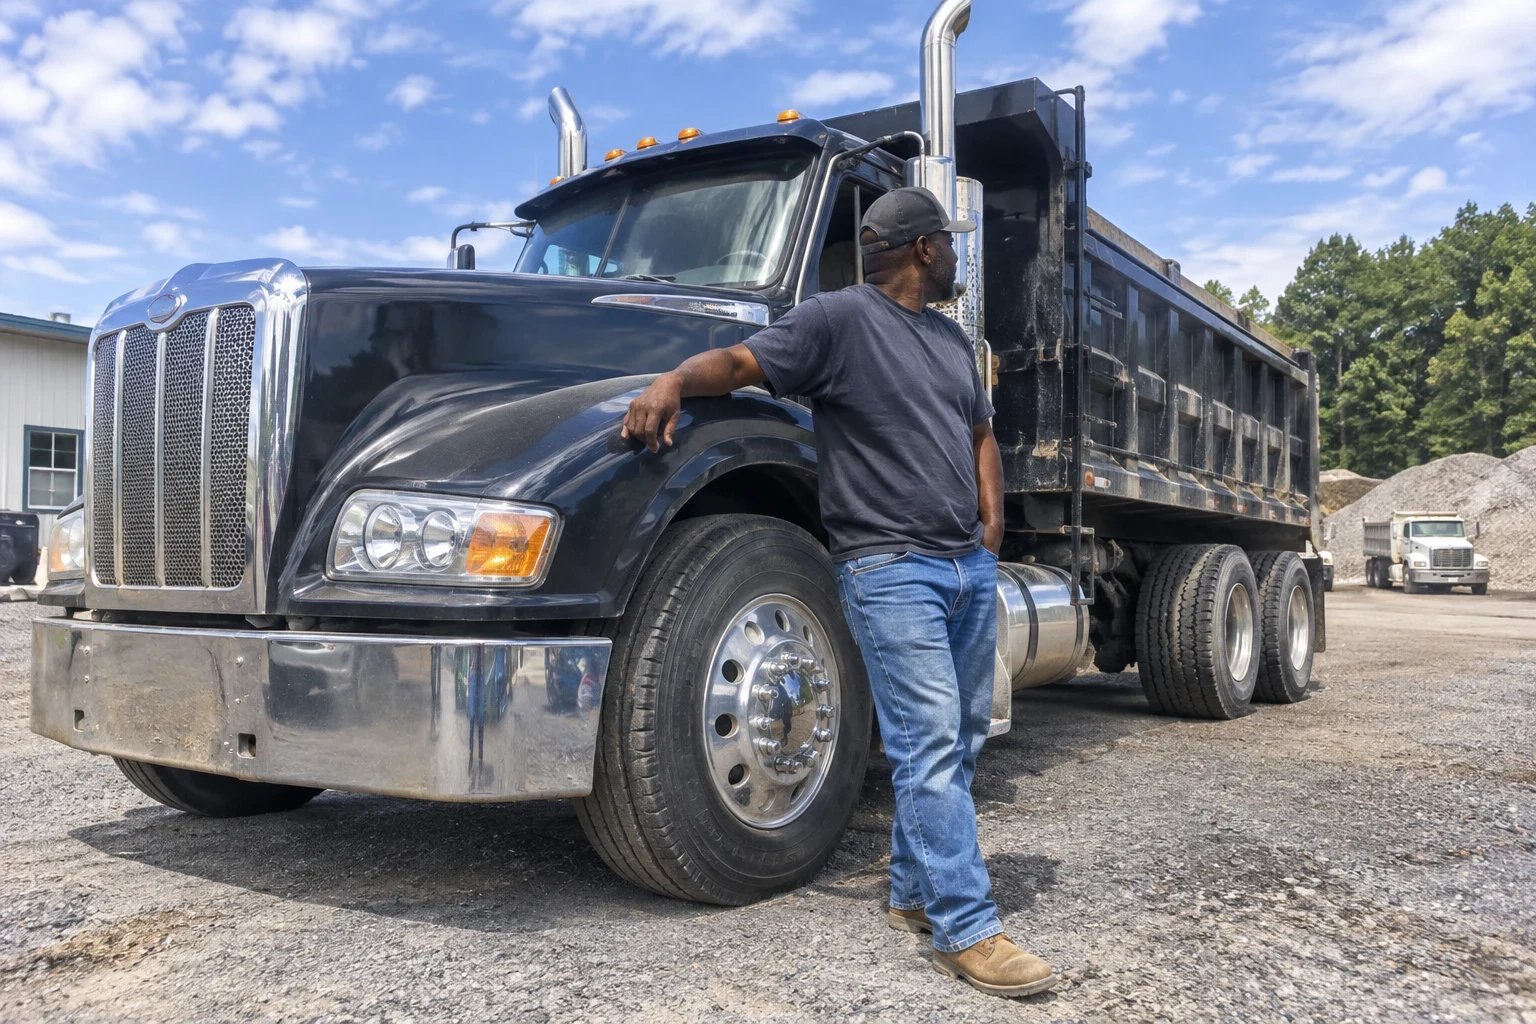
Dump Truck Insurance
Liability, physical damage and filings for dump trucks and construction trucks, with each option and its cost laid out plainly before you commit.
Hotshot Truck Insurance
Liability, physical damage and cargo coverage for pickup-and-trailer hotshot work, with your filings handled and every option explained before you choose.
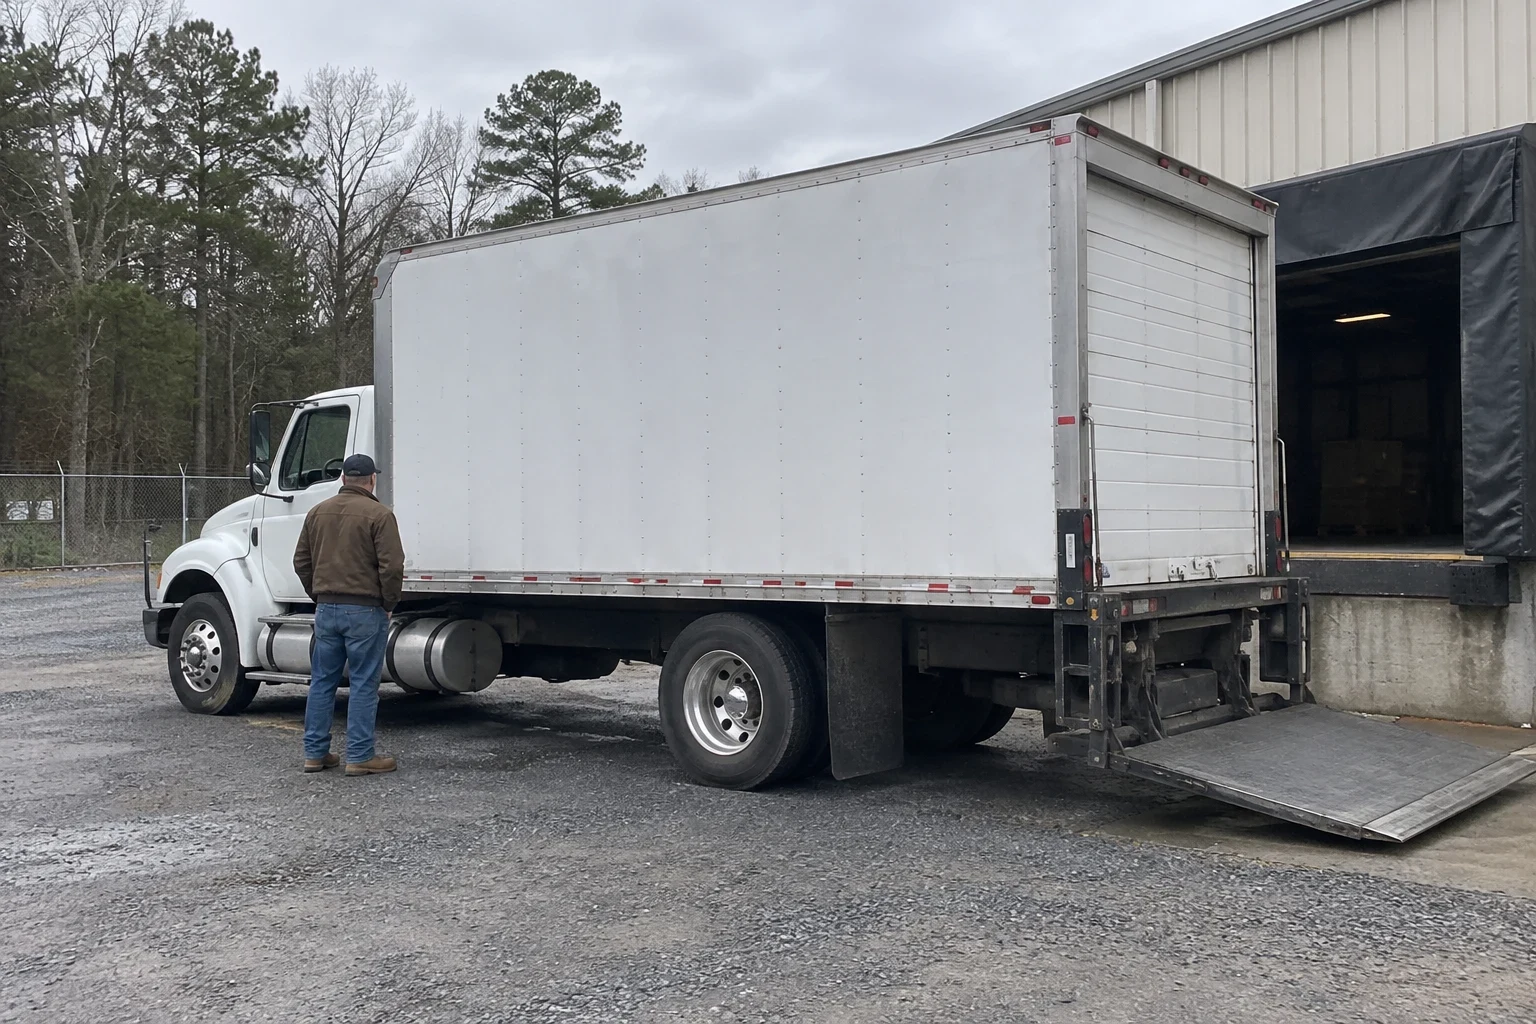
Box Truck Insurance
Liability, cargo and physical damage for straight trucks, explained coverage by coverage so your policy fits the freight you haul.
What Shapes Your Premium
Trucking premiums vary more than most people expect, even between two operators with the same truck. The price reflects how insurers read the risk of your operation. Knowing which levers matter helps you see where you have room to choose.
We build each quote from the details of your operation and show you how each coverage contributes to the total. If a change would lower the premium, we explain what you give up in exchange.
- What you haul
- General freight, refrigerated loads, building materials and auto haul all rate differently. High-value or theft-prone commodities raise cargo premiums in particular.
- Radius and lanes
- A local dump truck working jobs around the county is priced differently than a hotshot running across several states. Longer radius usually means more exposure and a higher liability premium.
- Drivers and their records
- Insurers look closely at each driver's age, CDL experience and motor vehicle record. A single recent violation can move the quote, so we ask for this information early.
- Time under your authority
- New authorities have no loss history yet, which insurers price cautiously. Clean loss runs over the first years tend to give you more choices at renewal.
- Equipment value and deductibles
- Physical damage is priced on the stated value of each truck and trailer. The deductible you choose shifts cost between the premium and your own pocket after a loss.
- Limits you select
- Carrying liability limits above the federal minimum, or raising cargo limits for a broker, adds cost. It may also open doors to better-paying freight.
Carriers We Work With Across West Metro Atlanta
Our office is in Douglasville, and we work with motor carriers throughout the surrounding area, including Lithia Springs, Austell, Powder Springs, Hiram and Villa Rica. We also serve operators in Mableton, Smyrna, South Fulton, Union City and East Point. Because quotes and reviews run by phone or video, your trucks do not need to be parked nearby for us to help.
- Douglasville
- Lithia Springs
- South Fulton
- Mableton
- Powder Springs
- Austell
- Smyrna
- East Point
- Union City
- Villa Rica
- Hiram
If you are based outside these towns but run Georgia freight, call and we will tell you plainly whether we can help.
How We Put a Policy Together
We treat a trucking policy the way a good builder treats materials. Each part has a job, a strength and a limit, and you should know all three before you sign.
Trade-offs laid out side by side
A higher deductible lowers the premium but raises what you pay after a loss. A stated value set too low saves money now and shortchanges you on a total loss. We put these choices next to each other so you can decide with the numbers in front of you.
Five years writing trucking coverage
We have been in business 5 years, working with motor carriers of every size from a single hotshot rig to small fleets. That time has taught us which questions shippers, brokers and lenders ask, and which gaps tend to show up only after a claim.
Sized to your contracts, not a template
Brokers often ask for a set cargo limit, and some shippers want more liability than the federal minimum. We read what your contracts require and match the policy to them, so a load is not held up over a certificate.
Paperwork handled with care
Filings for your MC authority, certificates of insurance for brokers, and requests to name a broker or shipper on your certificate are part of the work. We keep track of them so your DOT number stays in good standing with the right coverage on file.
A quiet review at renewal
Trucks get bought and sold, drivers change, and lanes shift. Before renewal we go back through your operation and adjust coverage, rather than simply rolling last year's policy forward.
Questions Truckers Ask Us
What coverage do I need to get my new MC authority active?
For most for-hire general freight carriers, the federal minimum is $750,000 in primary auto liability, and that coverage must be filed before your authority becomes active. Many brokers will also want motor truck cargo coverage at a limit they set. Physical damage is not required by regulators, but a lender will usually require it on a financed truck. We go through each of these with you on the first call.
Why is my quote higher than a friend's with the same truck?
Premiums depend on much more than the truck. Driver records, years under your authority, what you haul, how far you run, and the limits and deductibles you choose all change the price. We can show you which of those factors carry the most weight in your quote.
What is the difference between bobtail and non-trucking liability?
The terms are often used interchangeably, but they are not quite the same. Non-trucking liability covers a leased owner-operator when driving for personal use, off dispatch. Bobtail coverage is broader and can apply when running without a trailer under some circumstances. Your lease agreement usually decides which one you need.
I am leased to a motor carrier. What do I still need to carry?
The carrier you are leased to typically provides primary liability while you are under dispatch. You are often responsible for non-trucking liability, physical damage on your own truck, and sometimes occupational accident coverage. We read your lease with you to confirm what falls on your side.
Can you send certificates of insurance to my brokers?
Yes. Give us the broker or shipper name and any wording they need on the certificate, and we issue it. Keeping your certificates accurate is part of our regular service, not an extra.
Do I need trailer interchange coverage?
If you sign interchange agreements to pull trailers you do not own, the trailer owner will usually require it. It covers physical damage to that trailer while it is in your care. Without it, a damaged trailer can become a direct bill to you.
Do I have to come to your office?
No. Most clients work with us entirely by phone or video. Anyone who prefers to meet in person is welcome at our Douglasville office by appointment, which you can set up by phone.
A Small Agency That Knows Trucking
We are a trucking insurance agency based in Douglasville, and trucking is the only kind of coverage we write. Our clients are owner-operators, carriers just starting under their own authority, small and mid-size fleets, and businesses running hotshot, box truck and dump truck work.
We take a patient approach. A policy is only useful if you understand it before you need it, so we spend time explaining what each coverage does, where its edges are, and how your choices change the cost. You should never learn what your policy excludes for the first time after a claim.
- In business
- In business 5 years
See Every Coverage Clearly
Tell us about your trucks, drivers and freight, and we will walk you through each coverage and what it means for your premium. You make the decisions with every trade-off on the table.