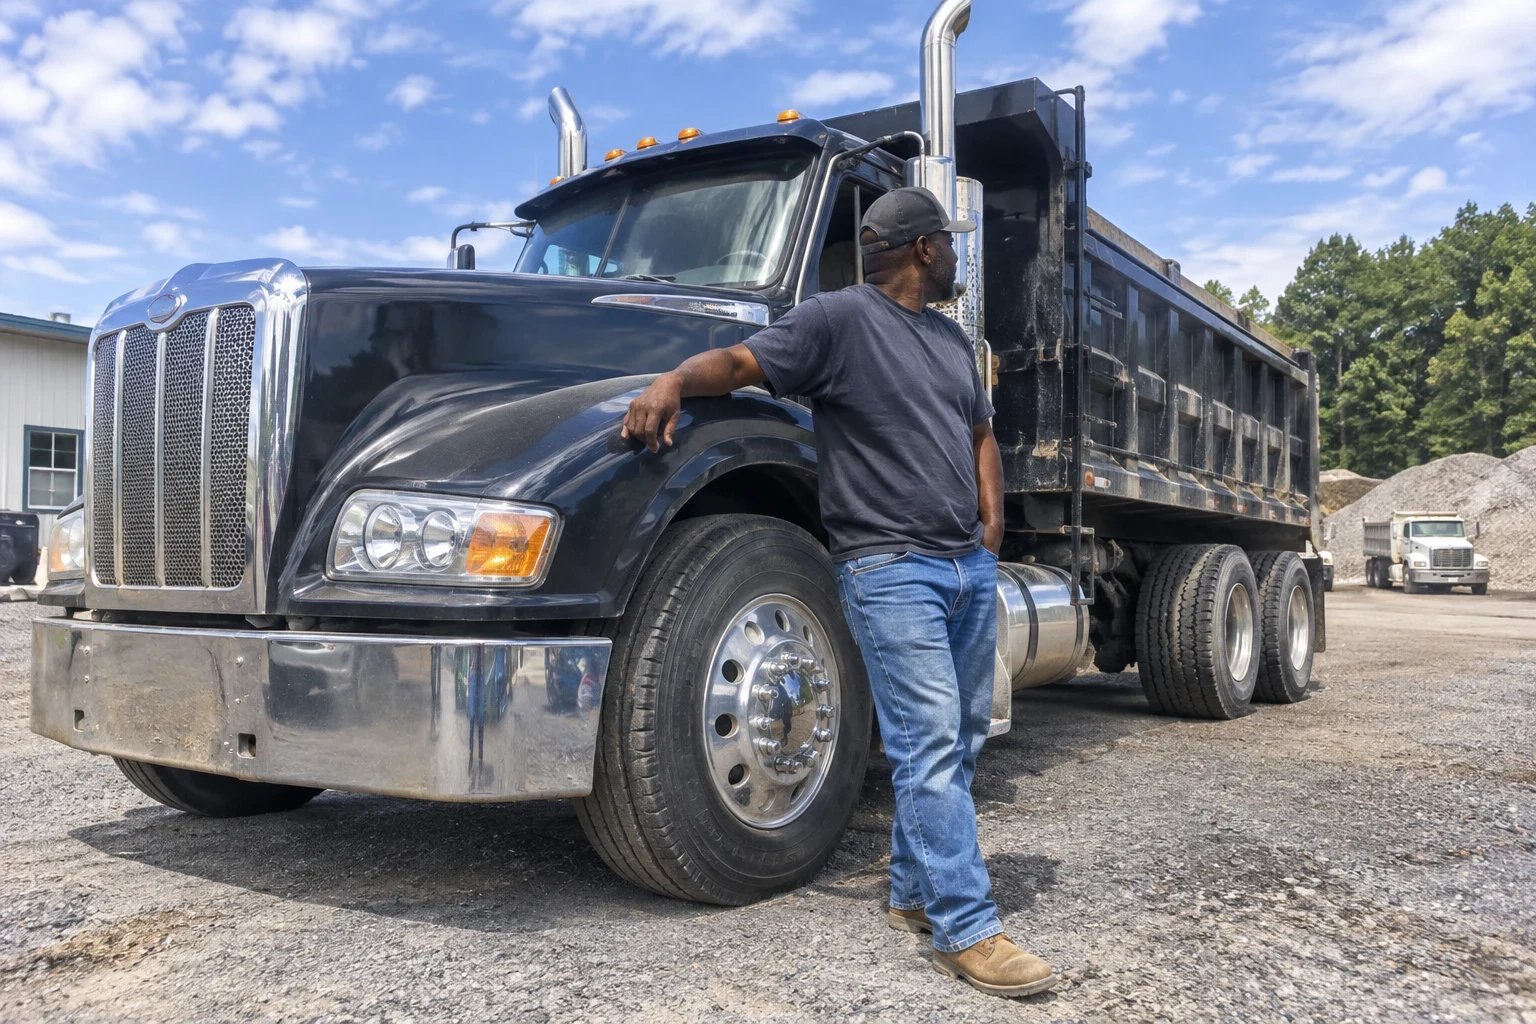
ServicesDump Truck Insurance
Dump Truck and Construction Truck Insurance in Douglasville
Dump trucks earn their keep on rough ground, short hauls and tight job sites. We put together coverage that fits how your trucks actually work, explain what each piece does and what it costs, and get your certificates out to the contractors who need them.
Coverage built around the work your trucks do
A tri-axle hauling gravel to a subdivision pad faces different risks than a highway tractor. Your trucks back up on soft ground, raise beds near power lines, and make many short runs a day. Underwriters price all of that, so the way your operation is described on the application matters as much as the trucks themselves.
We start with how you run: what you haul, how far, who drives, and which contractors you work for. Then we lay the options side by side, much like choosing materials for a build. Higher liability limits cost more but open doors to larger general contractors. Stated-value physical damage protects an expensive truck but adds premium. You see the trade-off before you decide.
What a dump truck policy usually includes
- Primary auto liability
- This pays for injuries and property damage your truck causes to others. Many general contractors and municipal jobs require higher limits than the legal minimum, so we check your contract requirements first.
- Physical damage on the truck
- Collision and comprehensive cover your own equipment, including rollovers on uneven fill and damage from falling debris. We help you set a stated value that reflects what the truck would truly cost to replace.
- Filings for your authority
- If you haul for hire under a DOT number or MC authority, certain filings must be on record. We make sure the right ones are submitted with your policy.
- Certificates of insurance
- Contractors often ask to be named on your policy before your truck rolls onto their site. We issue those certificates and keep the wording matched to what each contract asks for.
- Cargo coverage when it matters
- Most aggregate loads carry little value, but some haulers move materials a customer expects protected. We tell you plainly when motor truck cargo insurance is worth adding and when it is not.
Signs your current coverage needs a closer look
A contractor rejected your certificate
If a general contractor asked for higher limits or different wording naming them on your policy, your coverage may be holding back the work you can bid.
Your truck value changed
A new or rebuilt truck on an old stated value leaves you short after a total loss. The reverse also happens, and you pay for value you no longer have.
You started hauling farther or for hire
Moving from your own jobs to hauling for others, or crossing state lines, changes which filings and coverage apply.
Renewal jumped without explanation
A large increase usually traces back to a claim, a driver record or a change in how the truck is classified. We can review the reason with you.
What moves the price of dump truck insurance
Construction trucks are priced on how hard and how often they work. No two quotes look alike, because the truck, the driver and the jobs all feed into the premium. Here is what weighs most.
Truck type and value
A newer tri-axle or articulated hauler costs more to insure for physical damage than an older single-axle truck. Stated value drives that part of the premium directly.
Radius and type of hauling
Local runs between a quarry and nearby job sites price differently than long-distance or interstate work. Hauling demolition debris or asphalt can also shift the rate.
Driver records
Underwriters review every driver's motor vehicle record and experience in heavy trucks. One driver with recent violations can affect the whole policy.
Limits and deductibles
Higher liability limits and lower deductibles raise the premium. We help you match limits to the contracts you actually sign, not to a guess.
Claims history
Prior losses, especially rollovers and backing accidents, carry weight for several years. A clean record is worth protecting.
How we put your policy together
- 1
A conversation about your operation
We talk by phone, by video or at our office. You tell us what you haul, your usual radius, your drivers and the contracts you work under.
- 2
Gathering the details
We collect your DOT number, truck list with values, driver information and any loss runs from prior carriers. Clean, complete details tend to bring better terms.
- 3
Options laid out side by side
We present the coverage choices with their limits, deductibles and premium differences. You see what each option protects and what it costs to add or remove.
- 4
Binding and paperwork
Once you choose, we bind coverage, handle the required filings and send certificates of insurance to the contractors on your list.
Dump truck insurance questions
Do I need different insurance for a dump truck than a regular semi?
Often, yes. Dump trucks are rated in their own class, with different risks such as rollovers, bed raises and short repeated hauls. Some carriers specialize in construction trucks and others decline them, so where the policy is placed matters.
What liability limit do contractors usually ask for?
It depends on the contractor and the project. Larger general contractors and public jobs tend to require higher limits than the legal minimum. Send us the insurance section of the contract and we will compare it against your policy.
Is cargo coverage necessary for hauling dirt and gravel?
For most aggregate loads, the cargo itself is worth little, so many haulers skip it. If a customer requires it or you move higher-value materials, we can add motor truck cargo insurance. We will tell you which case fits your work.
Can you cover a single truck and also a small fleet?
Yes. We place coverage for single owner-operators and for growing construction fleets. As you add trucks, our fleet truck insurance options can bring all your units onto one policy.
How do I get a certificate to a contractor?
Give us the contractor's name and any wording they require, such as being named on your policy or a waiver of subrogation. We prepare the certificate of insurance and send it to them for you, so the paperwork is settled before your first load.
Get coverage that matches the jobs you bid
Have your truck list and driver information nearby. We will walk through the options, explain each trade-off and prepare your quote by phone.