ServicesMotor Truck Cargo Insurance
Motor Truck Cargo Insurance in Douglasville
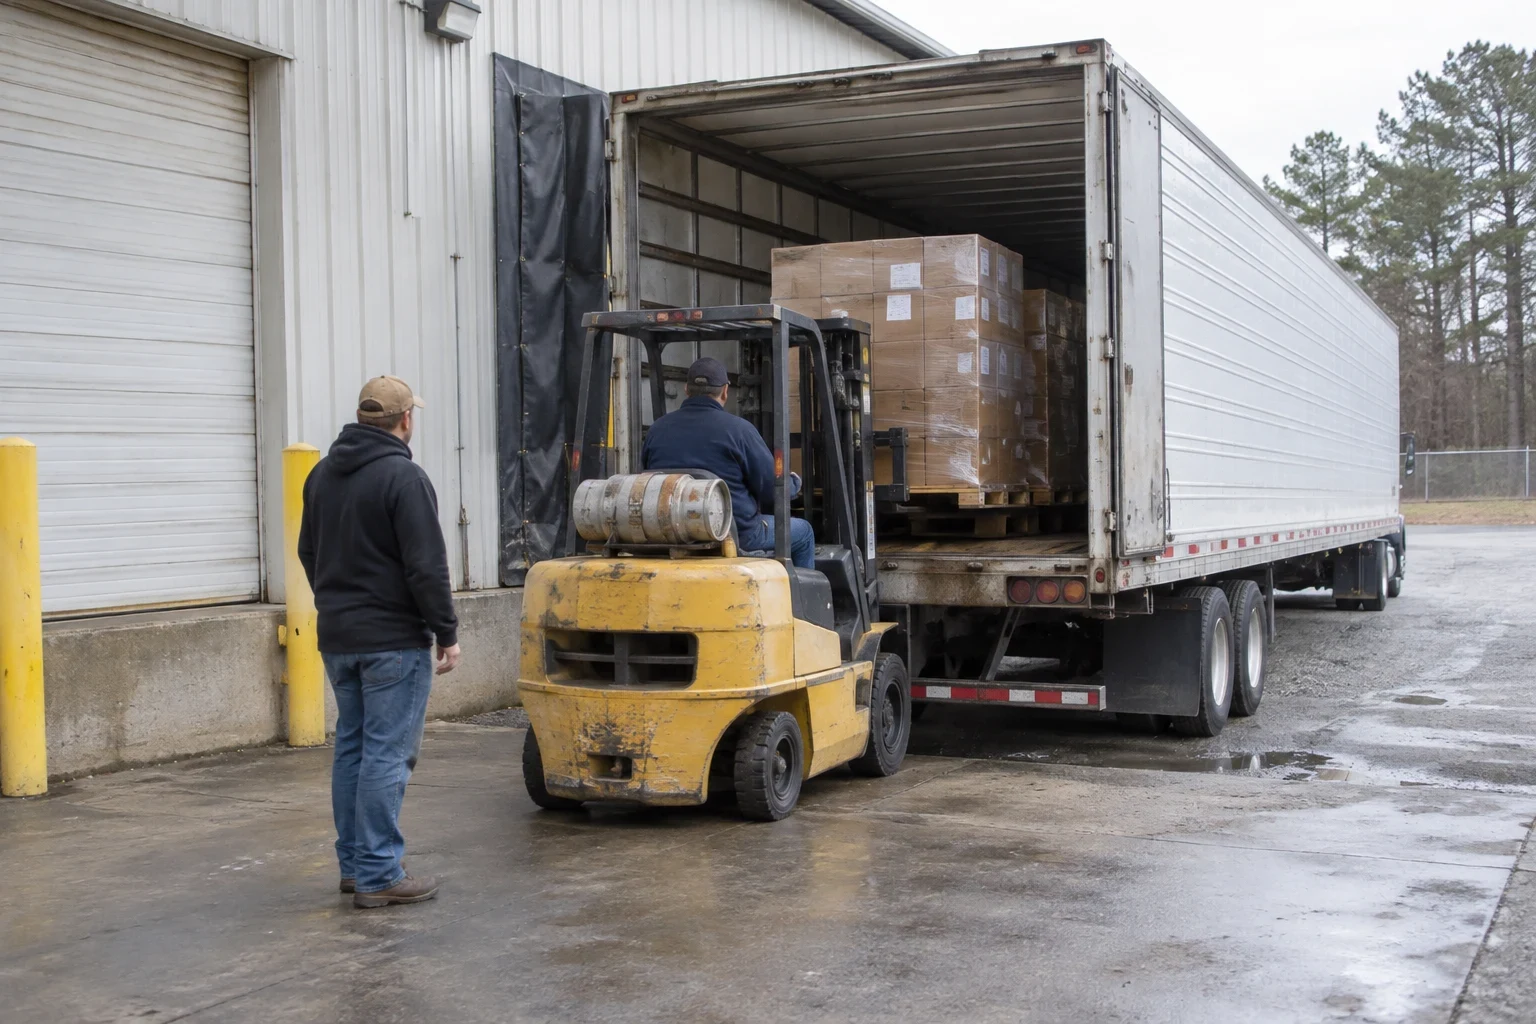
Cargo coverage pays when the freight on your truck is damaged or lost. We walk you through the policy forms, the commodity exclusions and the limit your brokers expect, so the coverage you carry fits the loads you actually haul.
What cargo coverage does, and where it stops
Motor truck cargo insurance protects the shipper's goods while they are in your care. If a load is damaged in a wreck, burns, gets wet or is stolen, the policy responds to the claim instead of your operating account. Most brokers will not tender a load until they have a certificate of insurance showing cargo coverage at the limit they require.
Two cargo policies can carry the same limit and pay very differently. A named perils form covers only the causes it lists, such as collision, fire and theft. A broad or all-risk form covers everything except what it excludes. The exclusions are where the real differences sit: unattended trucks, refrigeration breakdown, certain commodities and loads hauled outside a set radius.
We read those details with you before you buy. If you run along the I-20 corridor and take whatever the load boards offer, that matters more than the number on the certificate.
What we review when we set up your cargo coverage
- Policy form
- We explain whether a quote is written on a named perils or broad form and what that means for a claim. A cheaper premium often comes from a narrower form.
- Commodity list
- Many policies exclude or limit electronics, alcohol, tobacco, metals and other high-theft freight. We match the policy to the commodities you haul, so a load is not quietly excluded.
- Reefer breakdown
- Temperature-controlled freight needs refrigeration breakdown coverage, which is usually an added endorsement. We check the wording on mechanical failure and any reefer maintenance records the carrier expects.
- Theft and unattended vehicle terms
- Some forms pay theft only if the truck was locked, attended or parked in a secured lot. We point out those conditions so you can plan stops around them.
- Limits and deductible
- We set the per-load limit to cover your most valuable typical load and the limit brokers ask for. Then we weigh the deductible against what you can absorb on a small claim.
- Certificates and broker requests
- Once coverage is in place, we issue certificates of insurance to your brokers and shippers and handle requests to add them as certificate holders.
Signs your cargo coverage needs a closer look
A broker turned down your certificate
If a broker says your cargo limit is too low or a commodity is excluded, you are losing loads. That is usually fixable with a limit change or an endorsement.
You started hauling different freight
Moving from dry van general freight to refrigerated food, or from building materials to electronics, can put your loads outside the policy you bought.
You have never read the exclusions
Most cargo claim denials trace back to an exclusion the driver did not know about. A short review now costs far less than a denied claim.
Your loads are worth more than your limit
If a single load can exceed your per-load limit, the difference comes out of your pocket after a total loss.
You are adding trucks or trailers
Some cargo policies cover only scheduled units. A new trailer may need to be listed before its freight is covered.
How a cargo coverage review runs
- 1
A conversation about your freight
We start by phone, by video or at our office. You tell us what you haul, typical load values, your lanes and the limits your brokers require.
- 2
Reading your current policy
If you already carry cargo coverage, send us the policy. We go through the form, exclusions and endorsements and tell you plainly what is and is not covered.
- 3
Comparing quotes side by side
We present the quotes we gather with the form, limit, deductible and key exclusions laid out next to the premium, so you can see what each price actually buys.
- 4
Binding and paperwork
Once you choose, we bind the policy and send certificates of insurance to the brokers and shippers on your list. Later certificate requests go through us as they come in.
What moves the price of cargo coverage
Cargo premiums are set by how likely a claim is and how large it could be. The freight you haul matters most, followed by the limit you choose and your own history. We show you which of these you can adjust and which you cannot.
- Commodity
- High-theft and fragile freight costs more to cover than lumber or packaged dry goods. Refrigerated loads add the cost of reefer breakdown coverage.
- Limit and deductible
- A higher per-load limit raises the premium. A higher deductible lowers it, as long as you can comfortably pay that amount on a claim.
- Policy form
- A broad form with fewer exclusions usually costs more than a named perils form. The difference is often worth it for mixed freight.
- Claims and experience
- Past cargo claims, years under your own authority and driver records all shape how carriers price your operation. New authorities may see fewer options at first.
- Radius and lanes
- Long-haul runs and certain high-theft areas can raise the rate compared with local or regional work.
Cargo insurance questions we hear often
Something not covered here? (770) 525-6971
Is motor truck cargo insurance required by law?
For most general freight motor carriers, federal rules do not require a cargo filing. In practice, nearly every broker and shipper requires it before they will give you a load. We set your limit to match what your brokers ask for.
What cargo limit should I carry?
Start with the limit your brokers require, then check it against the value of your most expensive typical load. If a single load can be worth more than your limit, you would pay the difference after a total loss. We can help you weigh a higher limit against the added premium.
Does cargo coverage pay if my refrigeration unit fails?
Only if your policy includes refrigeration breakdown coverage, which is usually an endorsement. Many carriers also expect reefer maintenance records. We confirm the wording before you haul temperature-controlled loads.
Is cargo coverage the same as physical damage coverage?
No. Cargo coverage protects the freight you carry. Physical damage insurance protects your truck and trailer. Most operations need both, and we can review them together.
Can I add a broker as a certificate holder quickly?
Yes. Call us with the broker's name and details and we issue the certificate of insurance. Some brokers also ask to be named on the policy in other ways, and we tell you if a request needs an endorsement.
Know what your cargo policy covers before the next load
Tell us what you haul and which brokers you work with. We will go through the form, the exclusions and the limit with you and put a quote together by phone.